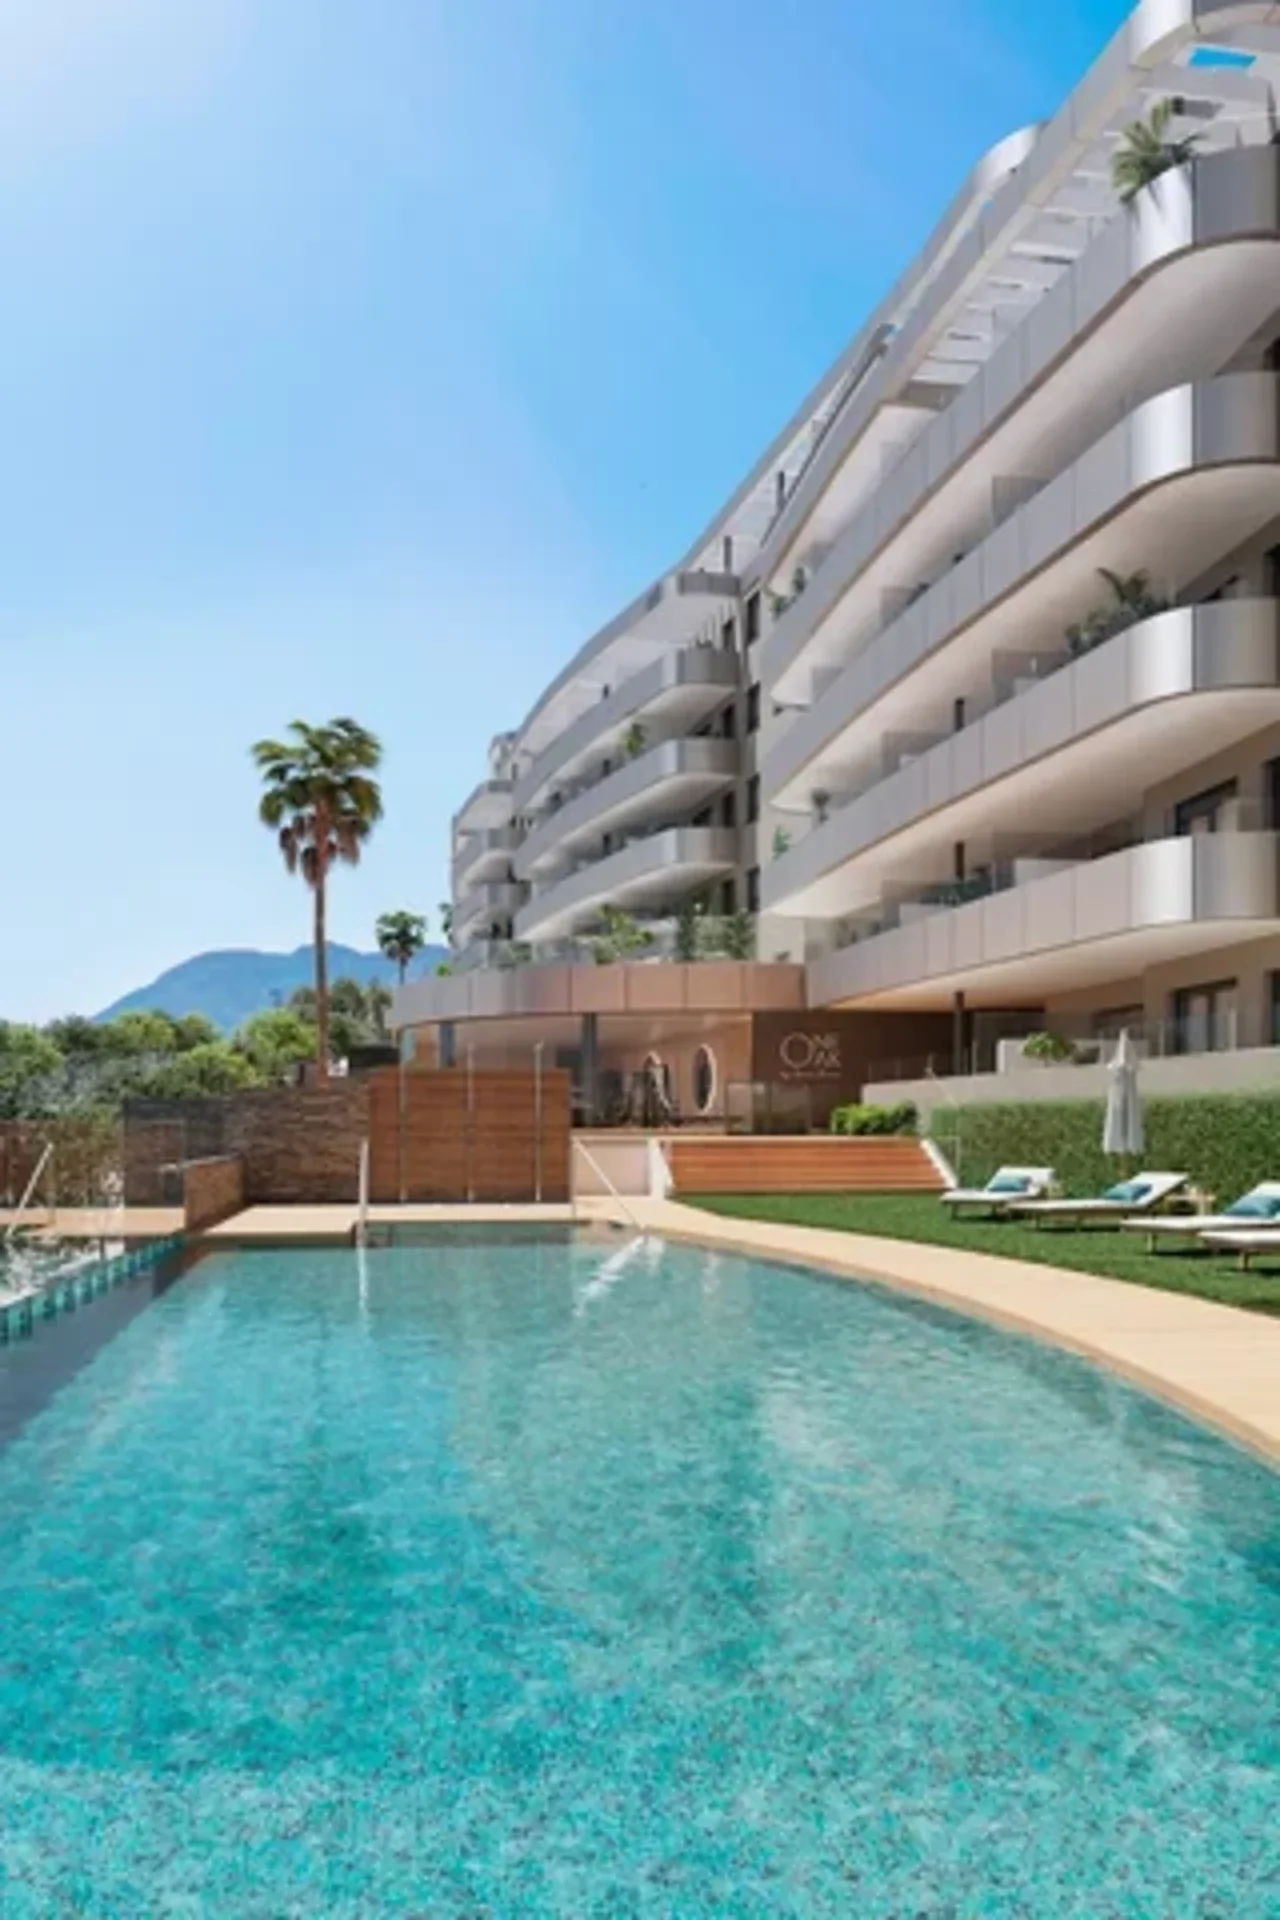
Quick answer: 9 verified new-build developments in Málaga province are listed on this page from €236 000, median €405 000, each checked for a bank guarantee and a written payment schedule. Málaga is the lowest coastal entry on the Costa del Sol and the only part of it that behaves like a working city rather than a resort, which is what keeps tenants through the winter.
Málaga Property for Sale: Current New-Build Stock
| Development | Town | Type | From | Developer |
|---|---|---|---|---|
| Zeta Place Málaga | Malaga | apartment | €236 000 | Aedas Homes |
| Zeta Crown Málaga | Malaga | apartment | €272 000 | Aedas Homes |
| Zeta Avenue Málaga | Malaga | apartment | €360 000 | Aedas Homes |
| Zeta Valley Málaga | Malaga | apartment | €365 000 | Aedas Homes |
| Kronos Malaga | Malaga Province | apartment | €405 000 | Kronos Homes |
| Malaga Towers Vision | Malaga | apartment | €408 000 | Metrovacesa |
| Bali Rincon | Rincon De La Victoria | apartment | €415 000 | Kronos Homes |
| Theater Square Malaga | Malaga | apartment | €530 000 | Grupo Insur |
| Malaga Towers Living | Malaga | apartment | €582 000 | Metrovacesa |
More Costa del Sol stock is on the regional page.
A City, Not a Resort
This is the distinction that decides whether Málaga suits you, and it is the one most foreign buyers arrive without. Marbella, Fuengirola and Torremolinos are resort economies: they fill in July and August, thin out by November, and their rental markets follow that curve however good the individual property is. Málaga is a provincial capital of roughly 580,000 people with a university, a container port, a regional hospital network and a technology cluster that has drawn international employers over the past decade. People live there in February. For a buyer that changes three things at once: the tenant is as likely to be a Spanish professional on a twelve-month contract as a Northern European on a fortnight’s holiday, the rental curve is flat enough that a long-let model works, and the resale pool includes domestic buyers.
This is the distinction that decides whether Málaga suits you, and it is the one most foreign buyers arrive without.
Marbella, Fuengirola and Torremolinos are resort economies. They fill in July and August, thin out in November, and their rental markets follow that curve however good the property is. Málaga is a provincial capital of roughly 580,000 people with a university, a container port, a regional hospital network and a technology cluster that has pulled in international employers over the last decade. People live there in February.
For a buyer that changes three things. The tenant is as likely to be a Spanish professional on a twelve-month contract as a Northern European on a fortnight’s holiday. The rental curve is flatter, so a long-let model actually works instead of being the fallback when the licence does not come through. And the resale pool includes domestic buyers, which insulates your exit from the sterling and dollar cycles that drive the resort strip.
Insider tip: the price gap between Málaga city and the western resort towns has narrowed since the AVE and the airport expansion, but it has not closed. Buyers comparing on price per square metre alone tend to miss that they are also comparing a twelve-month letting season against a five-month one.
What Your Money Buys
Our stock in Málaga province starts at €405,000 and the median across the wider Costa del Sol sits at €480,000, which places the city at the accessible end of a coast whose prime Marbella resale runs above €5,200 per square metre. At the median a buyer typically gets a two-bedroom new-build apartment with parking in a redevelopment district rather than in the historic centre, where new build effectively does not exist because there is nowhere left to build. The city divides into recognisable zones with materially different pricing: the Centro Histórico and Soho carry the tourist premium and the tightest licence restrictions, La Malagueta and Pedregalejo are established seafront addresses, and the eastern districts toward Rincón de la Victoria hold most new-build volume at the lowest entry with a longer commute.
Our stock here starts at €236 000 and runs to €582 000. The median of €405 000 typically buys a two-bedroom new-build apartment with parking in a redevelopment district rather than the historic centre, where new build essentially does not exist because there is nowhere to put it.
The city divides into recognisable zones. The historic centre and Soho carry the tourist premium and the tightest licence restrictions. The Malagueta and Pedregalejo seafront strips are established residential addresses. The eastern districts toward Rincón de la Victoria are where most new-build volume sits, with a longer commute and materially lower entry.
Purchase Costs
| Cost | New build | Resale |
|---|---|---|
| Tax | 10% IVA + 1.2% AJD | 7% ITP |
| Notary | €600 to €1,200 | €600 to €1,200 |
| Land registry | €400 to €800 | €400 to €800 |
| Independent lawyer | 1% to 1.5% | 1% to 1.5% |
On the median of €405 000 that is roughly €38,000 to €44,000 over the price for a new build. The cost of buying guide works a purchase through line by line.
Letting in Málaga
The licence position is stricter in the centre than the coast generally, because the city has been managing tourist pressure on the historic core since 2023. New VFT registrations are restricted in defined zones, and a community of owners can prohibit short letting in its statutes regardless.
That constraint is less damaging here than it would be in a resort town, because the long-let alternative is genuinely viable. A twelve-month contract to a Spanish tenant produces a lower gross than a licensed short let in peak season, and usually a better net once management at 22% to 28%, turnover cleaning, the empty shoulder months and the non-resident tax position are all applied.
Non-resident income tax remains 19% on net for EU and EEA residents and 24% on gross with no deductions for everyone else. For British and American owners that single line is often what makes the long-let route the better arithmetic. Run it through the gross versus net yield worksheet.
Connectivity, Which Is the Underlying Case
Connectivity is the least glamorous part of a property case and usually the most durable. Málaga-Costa del Sol is the third busiest airport in Spain and runs year-round schedules to most of Western Europe rather than the seasonal charter patterns serving smaller coastal airports, while the AVE high-speed line reaches Madrid in roughly two and a half hours. That matters well beyond convenience. Year-round flights are why the city keeps a foreign professional population through the winter, why the letting season does not collapse in October as it does in the resort towns to the west, and why the resale market still has active buyers in February. A case built on a five-month season depends on weather; one built on an airport with 12-month schedules depends on infrastructure, which is considerably more predictable.
That matters beyond convenience. Year-round flights are why the city keeps a foreign professional population through the winter, why the letting season does not collapse in October, and why the resale market has buyers in February. Infrastructure is the least glamorous part of a property case and frequently the most durable.
Buyer Scenarios in Málaga
Málaga is a city of 580,000 with a university, a port and a tech cluster rather than a resort, and the three scenarios that recur all follow from that.
The year-round income buyer. Someone who wants tenants on annual contracts instead of a holiday calendar. This is Málaga’s strongest case on the Costa del Sol: the tenant base is resident, the demand does not switch off in November, and the letting model does not depend on a tourist licence that the centre restricts in parts. Stock on this page starts at €236 000 with a median of €405 000, the lowest coastal entry on the coast.
The lowest-entry Costa del Sol buyer. Someone who wants the coast and the Andalucian tax position without Marbella or Estepona pricing. Resale carries ITP at 7%, new build 10% IVA plus roughly 1.2% AJD, and Patrimonio is rebated at 100% regionally, which removes the wealth tax for ordinary owners. What you give up against a resort address is the sea view; what you gain is a market that works in February.
The connectivity-led buyer. Someone whose model depends on being able to get here easily and often. Málaga airport is the structural asset under every other argument on this page, and it is what separates this market from the Almería coast at a similar price per metre. Check the winter schedule for your own route rather than the summer one before you assume the access holds all year.
What to Verify Before You Reserve
Zone comes first in Málaga, because the city restricts new VFT registrations in parts of the centre and a letting model built on an assumed licence can fail on address alone. The rest of this list is about matching documents to each other. Stock on this page starts at €236,000 with a median of €405,000, the lowest coastal entry on the Costa del Sol, and on a new build the promoting entity named on your reservation contract should be the same entity named on the bank guarantee. Where they differ, ask why before paying anything. The number most often overstated is the rent: model the realistic long-let figure for the specific district, which a city of 580,000 with a university and a port genuinely supports, rather than the peak-season short-let rate.
- Whether your specific zone is inside the restricted area for new VFT registrations.
- The community statutes on tourist letting, plus the last two AGM minutes.
- That the promoting entity on the reservation contract matches the guarantee issuer.
- Whether parking and storage are included or itemised separately.
- The realistic long-let rent for the district, not the peak-season short-let rate.
Steps common to every Spanish new build are in the non-resident buyer checklist.
Request a shortlist if you want the schemes that fit a specific budget and district.
Málaga District by District
| District | What it is | Entry level |
|---|---|---|
| Centro Histórico and Soho | Tourist core, tightest licence restrictions, no new build | Premium resale only |
| La Malagueta | Seafront, established, walkable to the centre | High |
| Pedregalejo and El Palo | Old fishing quarters east of the centre, low-rise | Upper mid |
| Teatinos | University district, modern blocks, student and staff tenants | Mid |
| Carretera de Cádiz | Dense western district, best long-let yields | Lowest in the city |
| Rincón de la Victoria | Coastal municipality east of the city, most new build | Mid, with a commute |
The pattern is the one you would expect in any European city and the one holiday buyers most often invert: the tourist core is the most expensive and the most restricted, while the districts that produce reliable rental income are the ones nobody photographs.
Comparing Málaga With the Resort Towns
| Málaga city | Marbella | Torremolinos | |
|---|---|---|---|
| Our entry price | €236 000 | €530 000 | €405 000 |
| Letting season | Year-round | Peak-weighted | Peak-weighted |
| Typical tenant | Spanish professional, student | International short-let | Mixed |
| Exit buyer pool | Domestic and foreign | Predominantly foreign | Mixed |
| Licence pressure | High in the centre, low outside | High | Moderate |
Marbella buys you an address with international resale liquidity and a premium to match. Málaga buys you a functioning urban economy at roughly half the entry. Neither is the right answer in the abstract: the question is whether your model depends on letting income through the winter.
Off-Plan in Málaga
5 of the developments listed here are off-plan. The protections are national rather than local: Ley 57/1968 requires every payment made before completion to be covered by a bank guarantee or insurance policy in your name, issued per payment rather than once for the scheme, and Ley 38/1999 adds a ten-year structural warranty from handover.
The practical failure is administrative rather than legal. Buyers hold a signed private contract and never receive the certificate for the second and third stage payments. Ask for the certificate each time you transfer, and check that the entity named on it matches the entity named on your contract.
Málaga’s new-build pipeline is concentrated in redevelopment plots and the eastern districts, which means build programmes of eighteen to thirty months are normal. Plan the currency exposure across that period rather than at the point of reservation.
The Wealth Tax Position
Andalucía applies a 100% rebate on the regional Patrimonio wealth tax, which removes it for ordinary owners. The separate state-level solidarity tax on large fortunes still applies above its own threshold, so this is a genuine saving on a normal purchase rather than a blanket exemption.
Combined with the flat 7% resale ITP, this makes Andalucía the cheaper side of the Andalucía-Valencia border on tax, which is worth putting into the comparison if you are genuinely undecided between the Costa del Sol and the Costa Blanca.
Also on the Market: Listed Developments
These are developments we have not yet run through our own checks. The figures below are the developer’s own published release data, recorded on the date shown. We have not verified the bank guarantee wording, the promoting entity, the community fee estimate or the licence position on these, which is the difference between this table and the one above. Ask us and we will run those checks against a specific unit before you commit to anything.
| Development | Location | From | Developer | Source |
|---|---|---|---|---|
| Creative Homes Bulevar II | Málaga | €285 000 | Neinor Homes | published 2026-09-06 |
| Creative Homes Bulevar | Málaga | €292 000 | Neinor Homes | published 2026-09-06 |
| Creative Homes Bulevar III | Málaga | €310 000 | Neinor Homes | published 2026-09-06 |
Frequently Asked Questions
Our verified new-build stock in Málaga starts at €236 000 and runs to €582 000, median €405 000. Málaga city is the lowest coastal entry point on the Costa del Sol: the same budget that buys a studio in prime Marbella buys a two-bedroom apartment here.
For net yield, usually yes. Málaga is a working city of some 580,000 people with a university, a port, a hospital network and a growing technology cluster, so it lets year-round to Spanish professionals and students. Marbella lets at higher rates for fewer weeks and depends on a licence regime that the municipality has been tightening.
New build carries 10% IVA plus 1.2% AJD stamp duty. Resale carries ITP at a flat 7% in Andalucía, one of Spain's lower rates. Notary, land registry and independent legal fees add a further 1.5% to 2.5%, so budget 10% to 13% over the price either way.
Only with a VFT registration from the Junta de Andalucía, and Málaga city has restricted new tourist registrations in parts of the centre. The community of owners can also prohibit short letting in its statutes by a 3/5 majority. Confirm both positions for your specific unit before reserving.
Málaga-Costa del Sol airport is the third busiest in Spain and serves most of Western Europe year-round, with the AVE high-speed line reaching Madrid in around two and a half hours. That connectivity is why the city holds tenants through the winter when the resort towns west of it empty out.
Get a Spain property shortlist
Tell us your budget and market (Costa Blanca, Costa del Sol, Balearic Islands). We reply within one business day with options matched to your goals.