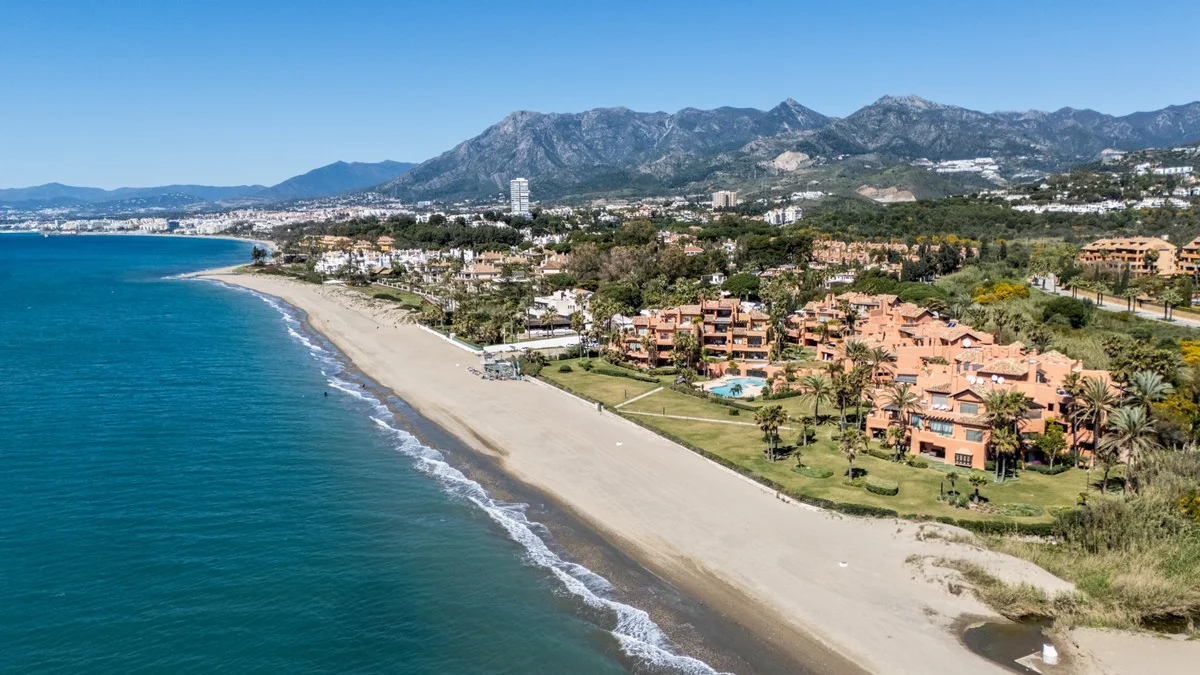
Quick answer: 65 verified new-build developments on the Costa del Sol are listed on this page, from €236 000 in Málaga city to €1 625 000 on the Marbella trophy strip, with a median entry of €480 000. 37 are off-plan and 23 are completed and key-ready. Purchase costs run 10% to 13% over the price, and every short-let plan needs a VFT registration that some municipalities now restrict by zone.
Costa del Sol Property for Sale: Current New-Build Stock
These are the developments we can quote on today, at the price the developer is selling at this release. Prices move with each phase, so read them as the entry point rather than a fixed figure.
| Development | Town | Type | From | Developer |
|---|---|---|---|---|
| Zeta Place Málaga | Malaga | apartment | €236 000 | Aedas Homes |
| Zeta Crown Málaga | Malaga | apartment | €272 000 | Aedas Homes |
| Vanian Gardens III | Estepona | apartment | €295 000 | Aedas Homes |
| Vanian Gardens Estepona | Estepona | apartment | €307 000 | Aedas Homes |
| Vanian Gardens IV | Estepona | apartment | €307 000 | Aedas Homes |
| Aedas Estepona | Estepona | apartment | €307 000 | Aedas Homes |
| Balance Nova Mijas | Mijas | apartment | €320 000 | Grupo Insur |
| Alianz Costa del Sol New Developments Hub Guide | Costa Del Sol | mixed | €360 000 | Alianz Group |
| Zeta Avenue Málaga | Malaga | apartment | €360 000 | Aedas Homes |
| Zeta Valley Málaga | Malaga | apartment | €365 000 | Aedas Homes |
| Alianz Fuengirola | Fuengirola | apartment | €380 000 | Alianz Group |
| South Bay Las Mesas | Estepona | apartment | €380 000 | Aedas Homes |
| South Bay Las Mesas II | Estepona | apartment | €385 000 | Aedas Homes |
| Almenara Homes | Estepona | apartment | €389 000 | Neinor Homes |
All 65 Costa del Sol developments are in the full new-build catalogue.
What the Coast Actually Costs
The Costa del Sol is not one market. It is a 150-kilometre strip where the price per square metre moves by a factor of four between Málaga city and the Marbella Golden Mile, and where the buyer profile changes with it.
Our own stock illustrates the spread. The cheapest entry in this catalogue is €236 000 in Málaga city, a working provincial capital with an airport, a university and year-round tenants. The most expensive is €1 625 000 west of Marbella, where the buyer is not underwriting yield at all but buying a recognised address with international resale liquidity. The median of €480 000 sits closer to the second group than the first, which tells you what kind of coast this is.
Málaga province recorded 36,117 residential transactions in 2025 with foreign buyers taking 32.80% of them, one of the highest sustained foreign shares anywhere in Spain. That number is a liquidity signal rather than a quality one: it means comparable sales and English-speaking professionals are easy to find, and it also means your eventual exit competes against other foreign sellers in the same currency cycle.
Insider tip: the price gap between Estepona and Marbella has narrowed over the last three years as the Estepona pipeline matured. If you are buying for capital preservation the Marbella address still carries the premium; if you are buying to let, the Estepona and Fuengirola corridor prices in a better yield-to-entry ratio.
Where the Stock Is
Of the 65 developments listed here, the pipeline concentrates in a handful of municipalities. Estepona and Marbella carry the deepest inventory, with Málaga city, Mijas and Fuengirola behind them. Six developers account for the entire list: Aedas Homes, Alianz Group, Grupo Insur, Kronos Homes, Metrovacesa, Neinor Homes.
That concentration matters when you compare. Two schemes from the same developer on the same coast will usually share a specification standard and a payment structure, which makes them genuinely comparable. Two schemes from different developers at the same price rarely are, and the difference tends to sit in the parking allocation, the appliance pack and the community fee estimate rather than in the headline.
Purchase Costs: the 10% to 13% Nobody Quotes
The developer quotes the unit price. The transaction costs more.
| Cost | New build | Resale |
|---|---|---|
| Transfer tax | 10% IVA | 7% ITP in Andalucía |
| Stamp duty (AJD) | 1.2% | not applicable |
| Notary | €600 to €1,200 | €600 to €1,200 |
| Land registry | €400 to €800 | €400 to €800 |
| Independent lawyer | 1% to 1.5% | 1% to 1.5% |
On a €480 000 purchase that is roughly €57,000 to €66,000 on top of the price for a new build. Model it in your year-one cash flow before you commit, not after the reservation is signed. The full cost breakdown works through a purchase line by line.
Short Lets: the VFT Question That Decides Your Yield
Any property let on a nightly basis in Andalucía needs a Vivienda con Fines Turísticos registration with the Junta de Andalucía. This is the single fact that most often breaks a Costa del Sol rental model after the deposit has moved.
Three things can stop you. The municipality can restrict new VFT registrations in specific zones, which Marbella and Málaga have both done. The community of owners can prohibit short lets in its statutes, and a 3/5 majority is enough to add that prohibition after you buy. And the unit itself must meet the technical requirements on ventilation, air conditioning, first-aid provision and guest information.
Confirm feasibility for your exact unit and building in writing before you reserve. A developer’s brochure saying the area is popular with tourists is not a licence. The Andalucía tourist licence guide sets out the process.
Net Yield, Not Brochure Yield
Gross yield marketing on this coast typically quotes 4% to 6%. Net yield after costs usually sits two to three percentage points below that.
What comes out: IBI (roughly €400 to €1,200 a year depending on cadastral value), community fees (€110 to €400 a month on a coastal block with a pool and gardens), insurance, management at 22% to 28% of gross for a short-let operation, and non-resident income tax at 19% for EU and EEA residents or 24% for everyone else, with no expense deductions available to the second group.
That last line is the one UK and US buyers most often miss after Brexit. A British owner letting a Costa del Sol apartment pays 24% on gross rental income with no deduction for the mortgage interest, the community fee or the management charge. Run the gross versus net yield worksheet with real figures before treating any brochure number as income.
Costa del Sol Towns
| Town | What it is | Our stock |
|---|---|---|
| Marbella | The benchmark address, deepest international resale pool | 14 |
| Estepona | The maturing alternative, best yield-to-entry on the west coast | 28 |
| Málaga | Working city, year-round tenants, lowest entry on the coast | 7 |
| Mijas | Inland and coastal split, golf and family buyers | 8 |
| Fuengirola | Dense seafront, strong long-let demand | 2 |
| Torremolinos | Regenerating, airport proximity | 3 |
| Benalmádena | Marina and hillside, mid-market | market guide |
| Nerja | Eastern cliffside, 25-40% below Marbella | market guide |
What to Verify Before You Reserve
Guarantee paperwork is the part of this list that protects actual money, and it is checked less often than it should be. Under the Ley 57/1968 regime each stage payment should carry its own certificate naming the buyer, the amount and the guaranteeing entity, issued per payment rather than as a single scheme-level document, and the promoting entity on your reservation contract should match the entity on that certificate. The rest is modelling discipline. Median price in our Costa del Sol catalogue is €480,000, and on a property at that level the annual running costs, IBI of roughly €400 to €1,200, community fees of €110 to €400 a month and management at 22% to 28% of gross for a short let, decide the net return far more than the headline yield does. Use the block’s real figures, not the brochure’s.
- That the promoting entity on the reservation contract matches the entity named on the bank guarantee.
- That every stage payment is covered by a Ley 57/1968 certificate, issued per payment and not per scheme.
- That VFT feasibility is confirmed for your exact unit and that the community statutes do not prohibit short lets.
- That the quoted price includes or itemises parking, storage and the appliance pack.
- That your net yield model uses the real IBI and community figures for the block, not the brochure gross.
Steps common to every Spanish new build are in the non-resident buyer checklist.
Off-Plan or Key-Ready: the Trade You Are Actually Making
37 of the 65 developments here are off-plan and 23 are completed. The choice between them is not about price, because on this coast they price within a few percent of each other. It is about who carries the risk.
Off-plan means you pay in stages against a build programme. You typically place 10% to 15% at reservation and private contract, then further stages through construction, then the balance at notary. In exchange you get first pick of floor and orientation, which on a coastal block moves the price by 10% to 20% between otherwise identical units, and you get eighteen to thirty months for your currency position to work for or against you.
What you carry is delivery risk. Spanish law protects you here through Ley 57/1968 and Ley 38/1999: every euro you transfer before the escritura must be covered by a bank guarantee or insurance policy naming you. In practice the protection is only as good as the certificate you actually hold, and the most common failure we see is a buyer with a signed contract and no per-payment certificate.
Key-ready removes the delivery question entirely. You see the finish, you measure the terrace, you meet the community, and you can start letting immediately if the licence position allows. You pay for that certainty by taking whatever floor and orientation is left.
Insider tip: ask the developer for two owner references from a delivered phase of the same scheme on the same coast. Finish quality between phases of one development differs more often than the marketing suggests, and owners will tell you things the sales office will not.
Financing as a Non-Resident
Spanish banks lend 60% to 70% of the lower of price or valuation to non-residents, against roughly 80% for residents. Two details catch buyers out.
The first is that the loan attaches to the completion balance, not to the off-plan deposits. If you are buying a €480 000 unit off-plan with a 40% stage schedule, you need €192,000 of your own capital before the mortgage does anything at all. The second is timing: a non-resident application with foreign income documentation runs six to ten weeks, and reservation contracts rarely allow that long. Start the application before you reserve, not after.
Valuation is done by a bank-appointed tasador and can come in below the purchase price on a rising market, which reduces the loan and increases your cash requirement at the worst moment. The non-resident mortgage guide covers the documentation set.
How a Costa del Sol Purchase Runs
| Stage | What happens | Typical timing |
|---|---|---|
| Reservation | €6,000 to €20,000, unit taken off market | Day 0 |
| Due diligence | Lawyer checks title, licence, guarantee, community statutes | 2 to 4 weeks |
| Private contract | 10% to 15% less the reservation, guarantee certificate issued | Week 3 to 5 |
| Stage payments | Against build milestones, certificate per payment | Through construction |
| Snagging | Defects listed and accepted before completion | 2 to 4 weeks before notary |
| Notary and registry | Balance paid, escritura signed, keys handed over | Completion |
The stage that gets skipped is snagging, and it is the only one you cannot go back for. Walk the unit with an independent surveyor, list every defect in writing, and make acceptance conditional on the list being cleared.
What You Will Not Find Here
We list new build from developers we have checked. We do not carry the resale stock that dominates parts of this coast, and on a page like this that is worth saying plainly: if you want a 2004 villa in Calahonda at €280,000, the portals have more of it than we do.
What we do instead is separate what we have checked from what we have not. A verified development has had its promoting entity matched against the guarantee issuer, its payment schedule confirmed in writing, its community fee estimate obtained and its licence feasibility checked with the municipality. A listed development carries the developer’s own published figures and none of those checks yet, and it says so. That distinction is why this page shows 65 developments rather than several thousand.
Request a shortlist if you want the two or three that fit a specific budget, town and letting plan.
Frequently Asked Questions
Our verified new-build stock runs from €236 000 in Málaga city to €1 625 000 for trophy coastal villas, with a median entry of €480 000. Prime Marbella resale sits above €5,200/m2 while Málaga province averages are materially lower. Entry price is the developer's current release price, not a fixed figure: each new phase is repriced.
Budget 10% to 13% over the price. New build carries 10% IVA plus 1.2% AJD in Andalucía. Resale carries ITP at 7% in Andalucía. On top of either, notary, land registry and independent legal fees typically add 1.5% to 2.5%. None of this is included in a developer's headline price.
Yes. Any property let on Airbnb or Booking.com in Andalucía needs a Vivienda con Fines Turísticos registration with the Junta de Andalucía. Individual municipalities can restrict new registrations by zone, and community of owners statutes can ban short lets outright. Confirm feasibility for your exact unit before you reserve, not after.
In our catalogue Estepona and Marbella carry the deepest pipelines, followed by Málaga city, Mijas and Fuengirola. Of the 65 developments listed, 37 are off-plan and 23 are completed and key-ready, which matters because off-plan requires Ley 57/1968 guarantee checks on every stage payment.
Spanish banks typically lend 60% to 70% of valuation to non-residents, against 80% for residents. The loan applies to the completion balance, not to off-plan stage deposits, which you fund from your own capital. Approval takes longer than a UK or Irish equivalent, so start it before you reserve.
Get a Spain property shortlist
Tell us your budget and market (Costa Blanca, Costa del Sol, Balearic Islands). We reply within one business day with options matched to your goals.