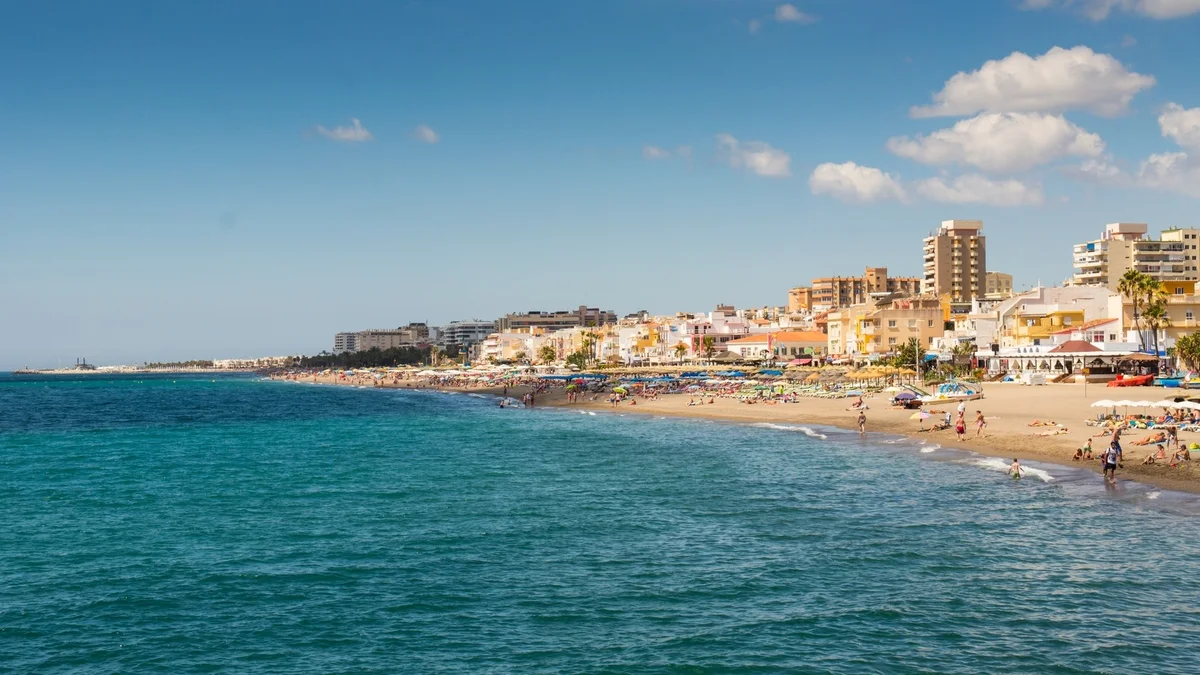
Quick answer: These two neighbours in the Málaga airport corridor are the Costa del Sol’s entry point, and the useful question is narrow: what net yield does sub-€250,000 stock actually produce here, once management, community charges and non-resident tax are taken out? Both have rail access and year-round trade. Torremolinos is denser, cheaper per square metre and more rental-oriented; Benalmádena is spread across three distinct zones with a family-tourism profile and higher community charges. The gross figures look similar and the net figures do not.
Why net yield, and why this price band
At this end of the Costa del Sol the entry ticket is low enough that gross yield looks attractive on almost any listing, and low enough that fixed costs bite disproportionately. A community charge of €150 a month is 1.4% of a €130,000 apartment’s value and 0.6% of a €330,000 one. The same euro cost removes more than twice as much yield from the cheaper property.
That is why comparing these two towns on gross returns is actively misleading, and why the sub-€250,000 band deserves its own analysis rather than an extrapolation from Marbella.
| Torremolinos | Benalmádena | |
|---|---|---|
| Structure | Dense, continuous urban front | Three distinct zones: Costa, Pueblo, Arroyo de la Miel |
| Typical stock at this budget | Compact apartments, older blocks and refurbished | Resort-style schemes and apartments across the zones |
| Community charges | Generally lower; fewer resort amenities | Often higher; pools, gardens, some with concierge |
| Rail access | Cercanías, direct to airport and Málaga city | Cercanías at Arroyo de la Miel |
| Demand profile | Rental-oriented, high turnover, year-round | Family tourism, marina and attractions, year-round |
| Price per m² | Lower | Higher in Costa and marina zones |
Send us an address in either town and we will build the net figure with the actual community charge, IBI, management quote and the correct non-resident tax rate for your nationality.
Get a net-yield model on a specific sub-€250k unitA worked comparison at €200,000
Two apartments, same budget, carried to what reaches the owner.
Torremolinos, one-bedroom near the centre, €200,000. Acquisition at Andalucía’s flat 7% ITP plus notary, registry and legal work commits roughly €217,000. Licensed short letting in a high-turnover town might gross €14,000 across a long season. Management at 24% of gross takes €3,360. A modest community charge of €90 a month is €1,080, IBI, insurance and maintenance add perhaps €1,700, so costs total around €6,140. That leaves €7,860 before tax, or about €6,367 after 19% for an EU-resident owner: roughly 2.9% on committed capital.
Benalmádena, one-bedroom in a resort scheme with pool and gardens, €200,000. The same acquisition arithmetic commits roughly €217,000. Gross might be similar at €14,000, or slightly higher on a marina-adjacent unit. But a community charge of €165 a month is €1,980, nearly double, and resort schemes carry higher maintenance provisions. Costs total around €7,100, leaving €6,900 before tax, or about €5,589 after 19%: roughly 2.6%.
The gross figures were identical. The net figures differ by around 0.3 percentage points, entirely because of the community charge. Over a ten-year hold that is real money, and it is knowable before you buy from a single document.
A non-EU owner should rerun both. Taxed at 24% of the €14,000 gross with nothing deductible, they pay €3,360 and keep about €4,500 in Torremolinos and €3,540 in Benalmádena, roughly 2.1% and 1.6%. The nationality swing is larger than the town swing, and no feature of either property changes it.
What do the three zones of Benalmádena mean?
Benalmádena is treated as one market and is not one. Benalmádena Costa is the seafront and marina strip, the most expensive and most tourism-dependent. Benalmádena Pueblo is the hillside old village, quieter, with views and less rental demand. Arroyo de la Miel is the inland commercial centre, where the Cercanías station sits and where most year-round residents live.
For an investor those are three different propositions. Arroyo de la Miel offers the rail access, the resident tenant base and the long-let fallback. The Costa offers the highest short-let rates and the highest charges. The Pueblo offers neither strong yield nor easy letting, and is bought for use.
Torremolinos is more continuous, which is why the comparison is easier to make there: a unit near the centre has rail access, beach access and year-round trade in one place.
- If the model needs long-let fallback, Arroyo de la Miel and central Torremolinos are the two candidates.
- If the model is short-let only, Benalmádena Costa produces the higher rate at the higher cost base.
- If the property is for use, Benalmádena Pueblo is the pleasant option and the weakest investment.
- In all cases, the community charge is the number that decides the outcome at this ticket size.
Do the taxes or licence rules differ?
No: they share a regional tax authority, and neighbouring municipalities on this stretch of coast could not diverge on rates if they wanted to.
| Line | Torremolinos and Benalmádena |
|---|---|
| New build | 10% IVA plus 1.2% AJD |
| Resale | ITP at Andalucía’s flat 7% |
| Notary, registry, legal | roughly 1.5% to 2.5% |
| Short-let licence | VFT registration with the Junta de Andalucía plus municipal compatibility |
| Non-resident rental tax | 19% of net for EU and EEA residents, 24% of gross otherwise |
On a €200,000 resale the ITP is €14,000 in either town, with the full acquisition block running roughly €20,000 to €26,000 including fees. Budget it as cash; no Spanish mortgage finances it.
Since 2019 a community has been able to shut tourist letting down by qualified majority, and the restriction survives a change of owner. That risk is unusually live at this price point, because €150,000 to €250,000 blocks in both towns hold a high proportion of long-term residents and retired owner-occupiers, the demographic most likely to vote for quiet.
Red flag: two things at this price point. A holiday-let claim with no VFT number behind it, and a community charge given as a round approximation. At €200,000 the community fee is a large fraction of net yield, and an estimate that has never been checked against the administrator’s statement is where the yield model quietly breaks.
Insider tip: get the community’s actual budget rather than the fee quoted in the listing. At €200,000 a difference of €100 a month in community charges is €1,200 a year, which on a 6% gross yield is a full percentage point of return, and it is the single largest controllable variable in this comparison. Ask for the budget, the reserve fund balance and the last two annual meeting minutes before you compare the two towns on price.
Where does the net yield actually leak at this price?
At €200,000 the gap between gross and net is proportionally wider than at any higher price point, because most of the costs of owning a Spanish apartment are set by the building rather than by the value of your share of it.
Work through where the money goes on a licensed unit grossing, say, €14,000 across a season:
| Line | Typical scale at €200,000 | Why it bites here |
|---|---|---|
| Community charge | The single largest fixed cost | A pool, lift and gardens cost the same to run whether the flat is worth €200,000 or €600,000 |
| IBI | Modest, set on cadastral value | Predictable, rarely the problem |
| Management | Around a fifth of gross on a short let | Changeover-driven, so it scales with turnover rather than with rent |
| Maintenance provision | Underprovisioned by most buyers | Older stock consumes it faster |
| Vacancy | Season-dependent | Two lost weeks is a large share of a short season |
| Non-resident tax | 19% of net inside the EU and EEA, 24% of gross outside | The gross basis is brutal on a high-turnover unit |
The line to concentrate on is the first. A community charge of €150 a month is €1,800 a year, which on €14,000 of gross is nearly 13% of income before anything else is paid, and the identical charge on a €600,000 apartment in the same building would be under 5% of its rent. Fixed costs are regressive across price bands, which is why entry-level coastal stock so often disappoints against its headline yield while the brochure arithmetic looks fine.
This is also why the community charge must come from the administrator’s statement rather than from the listing. A figure quoted as “approximately” is usually the one that has not been checked, and at this price band a €40 monthly difference is worth more than a percentage point of net yield.
At the sub-€250,000 level the fixed costs decide the return, because they do not scale down with the purchase price. A €200,000 apartment carries IBI of roughly €400 to €1,200 a year, community fees of €110 to €400 a month, insurance, and management at 22% to 28% of gross on a short-let operation, and that stack consumes a far larger share of the income than it would on a €500,000 property. Torremolinos generally carries lower community charges on denser stock; Benalmádena’s resort communities with pools, gardens and lifts carry higher ones. Both are in Málaga province, so a resale costs 7% ITP either way and the difference in return comes entirely from the annual line. Non-resident income tax then takes 19% of net from an EU or EEA owner and 24% of gross from everyone else.
What does the age of the building do to your costs?
The two towns’ stock has different vintages, and vintage drives the cost line that ruins more entry-level investments than any other: the derrama.
Torremolinos built much of its apartment stock during the tourism boom of the 1960s and 1970s. Buildings of that age reach the point where lifts, façades, roofs, plumbing risers and communal terraces all need replacing at roughly the same time, and Spanish buildings of a certain age are subject to periodic technical inspection which converts deferred maintenance into scheduled obligations. When the community votes the works through, every owner is levied by participation quota, a sum with no relation to whether the flat is let that year.
Benalmádena’s stock is more mixed. Arroyo de la Miel and parts of the Costa contain considerable later construction, and a building from the 1990s or 2000s is typically a decade or more away from the same cycle.
Three things follow for a buyer at this level:
- A low community charge in an old building is a warning, not a bargain. It often means the reserve fund is thin and the works are still ahead.
- The minutes of the last two general meetings are where a derrama first appears, usually as a survey commissioned or a quote discussed, months or years before it becomes a levy.
- Ask for the reserve fund balance. A community with real reserves has already priced its future works into your monthly charge; one without has priced them into a bill you have not yet received.
Neither town is the safer choice in the abstract: a well-maintained 1970s block with a funded reserve beats a neglected 1990s one. But the base rate differs, and a buyer comparing two apartments at the same price in the two towns is very likely comparing two different positions in the maintenance cycle without knowing it.
Building age drives the running cost more than location does at this price level. Older blocks in both towns carry lifts, roofs, pools and pipework approaching renewal, and an underfunded reserve turns that into a special levy landing on the owner of record rather than on the seller. Newer stock carries higher community fees monthly but fewer surprises. On a €200,000 apartment the difference between €110 and €400 a month in fees is €3,480 a year, which is more than a full point of gross yield either way. Ask for the annual budget, the reserve fund balance and the last two annual meeting minutes in both towns before comparing anything else. Both towns charge 7% ITP on a resale and 10% IVA plus roughly 1.2% AJD on a new build, so nothing in the acquisition arithmetic separates them at all.
What would change this answer?
This page argues that at €200,000 the net yield, not the town, decides the outcome. Three circumstances change that:
- If you buy in cash and use the property yourself for part of the year. Then the fixed costs are partly a lifestyle expense rather than a drag on yield, and the calculation above overstates the problem.
- If the building has just completed its major works. A block that has recently renewed its lift, façade and roof carries a much lower forward cost than its age suggests, and it is usually cheaper than an equivalent that has not, which is the closest thing to a free lunch at this price point.
- If you intend a long-term tenancy rather than a short let. Management falls sharply, vacancy nearly disappears, and the changeover-driven costs go with them. Gross income drops, but at this price band the net figures converge, and the long-let version is considerably less work.
What does the airport corridor position give you?
Both towns sit within a short Cercanías ride of Málaga airport, and that is their shared structural advantage over the rest of the coast. A guest can arrive without hiring a car, which sustains short-break demand through the shoulder months and into winter in a way that road-only towns further west cannot match.
It also supports a genuine long-let market: airport, hotel and hospitality staff working in the corridor, plus Málaga city commuters priced out of the city. That gives both towns a fallback if a licence is refused or a season disappoints, which is worth more at this ticket size than a higher peak rate.
Málaga province recorded a 32.80% foreign-buyer share across 36,117 residential transactions in 2025. At the sub-€250,000 end of that market, buyers are a mix of international purchasers and domestic Spanish buyers, which broadens the exit compared with the prime end of the coast.
Neither town ever ran on residency demand, prices here sat well below the old qualifying threshold, so the 2025 closure of the property route passed through this end of the coast almost unnoticed. What drives both is holiday use and yield.
Who rents here, and for how long?
The tenant profile at this end of the coast is more varied than a holiday-let model implies, and knowing who is available to you is what makes the fallback real rather than theoretical.
Three distinct groups take property in both towns. Holiday visitors are the group the yield models assume: high nightly rates, short stays, concentrated in a season, and dependent on a licence. Seasonal workers in hospitality and services need somewhere to live from spring to autumn, and will take a six or nine-month let at a rent between the holiday and the annual figure. Permanent residents, Spanish households, retired foreign owners’ families, and the year-round workforce that keeps the coast running, take twelve-month tenancies at the lowest rate but with the least management and the least risk.
Both towns have all three. What differs is the mix, and it follows the transport. Torremolinos and Arroyo de la Miel sit on the Cercanías line into Málaga, which makes them commutable and gives them a genuine year-round residential tenant base that the coastal strip further from the station does not have to the same degree.
The practical implication is about resilience rather than income. A property that can be let to any of the three groups has three chances to be occupied; one that only works as a holiday let has one, and it depends on a permission that a community vote can remove. At €200,000, where the fixed costs described above run whether the unit is let or not, the difference between three fallbacks and none is larger than the difference between the two towns’ gross yields.
Ask, then, not only what a property earns in August but who would take it in February, and whether the answer requires a licence.
Which town suits which buyer?
Torremolinos suits an investor optimising net yield at a low entry ticket; a buyer who wants rail access, beach and year-round trade in one continuous town; and anyone who would rather hold a plain apartment with a low community charge than a resort unit with a high one.
Benalmádena suits a buyer who wants resort amenities and is willing to pay for them in the monthly charge; someone targeting Arroyo de la Miel specifically for its rail access and resident base; and a lifestyle purchaser drawn to the Pueblo or the marina.
Neither suits a buyer comparing gross yields, because at this price band the community charge decides the outcome and it does not appear in a gross figure.
What does the seafront itself contribute?
One physical factor separates these two towns and it works directly on lettability: the shape of the coast.
Torremolinos has a long, continuous promenade linking its beaches, walkable end to end, with the town’s commercial life running alongside it. A property near that promenade is near everything, and guests who arrive without a car can function.
Benalmádena’s coastline is more segmented, and its marina forms a distinct destination with its own restaurants and moorings rather than a continuation of a single seafront. That gives Benalmádena a stronger point of interest and Torremolinos a stronger continuous walkable strip.
For letting, walkability tends to matter more than a destination does. Guests booking a two-bedroom apartment at this price point are rarely arriving by boat, and the reviews that drive future bookings turn on whether the beach, a supermarket and somewhere to eat are within a few minutes on foot. Measure that on the map before you accept a description of a property as beachfront.
Which buyer scenarios does each suit?
Torremolinos suits the buyer working at the sub-€250,000 band who needs the net yield to survive the costs. Denser stock, a lower price per m2 and lower community charges all push in the same direction, and both towns sit on the Cercanías line minutes from Málaga airport, so neither pays an access penalty.
Benalmádena suits the buyer who wants a specific one of its three zones, Costa, Pueblo or Arroyo, and understands that they are three different markets rather than one town. Choosing the zone before choosing the property is the whole exercise here.
Neither suits a buyer who has modelled a gross yield at this price band without the community fee, the IBI and the management charge in the same calculation. At €200,000 those three costs are a far larger share of the return than they are at €500,000, which is why a gross comparison at this level is close to meaningless.
What to verify before you offer
- Get the community charge from the administrator’s statement, not the listing, plus what it covers and the reserve fund position.
- Ask for the minutes of the last two general meetings, where both special levies and tourist-let restrictions appear first.
- Obtain the VFT registration number for the exact property and verify it with the Junta de Andalucía.
- Establish which Benalmádena zone a property sits in, because Costa, Pueblo and Arroyo de la Miel are three different markets.
- Time the walk to the nearest Cercanías station, because the rail premium depends on that distance.
- Rebuild the net income using the community charge you obtained in step 1 rather than the listing’s figure, then tax it on your own basis, at this price point the community charge alone can move net yield by half a point.
- Establish whether the purchase is a resale at 7% ITP or a first transfer at 10% IVA plus 1.2% AJD.
- Appoint independent legal representation before any money moves. At this price band the reservation fee is large relative to the purchase, and it is the sum most often lost by buyers who instructed a lawyer afterwards.
Both towns sit at the entry end of a coast whose upper end is covered in Marbella against Estepona. District pricing is in our Torremolinos analysis and our Benalmádena analysis, and the Costa del Sol investment guide covers the region.
Frequently Asked Questions
Torremolinos, typically by around 0.3 percentage points, and almost entirely because of the community charge. On identical gross rent of €14,000, a €90 monthly charge against €165 changes the net outcome more than any difference in rates or occupancy between the towns.
Because it is a fixed euro cost against a low asset value. €150 a month is 1.4% of a €130,000 apartment and 0.6% of a €330,000 one. At the sub-€250,000 end of the Costa del Sol the charge removes more yield than anything else on the statement.
Yes. Benalmádena Costa is the seafront and marina, most expensive and most tourism-dependent. Arroyo de la Miel is the inland commercial centre with the Cercanías station and the resident tenant base. Benalmádena Pueblo is the hillside village, bought for use rather than yield.
No. Both are in Málaga province within Andalucía: 10% IVA plus 1.2% AJD on new build, a flat 7% ITP on resale, plus roughly 1.5% to 2.5% for notary, registry and legal work. On a €200,000 resale the ITP is €14,000 in either.
Two things. Guests can arrive by Cercanías without hiring a car, which sustains short-break demand through the shoulder months. And the corridor's airport, hotel and hospitality employment supports a genuine long-let tenant base, giving you a fallback if a licence is refused or a season disappoints.
Get a Spain property shortlist
Tell us your budget and market (Costa Blanca, Costa del Sol, Balearic Islands). We reply within one business day with options matched to your goals.