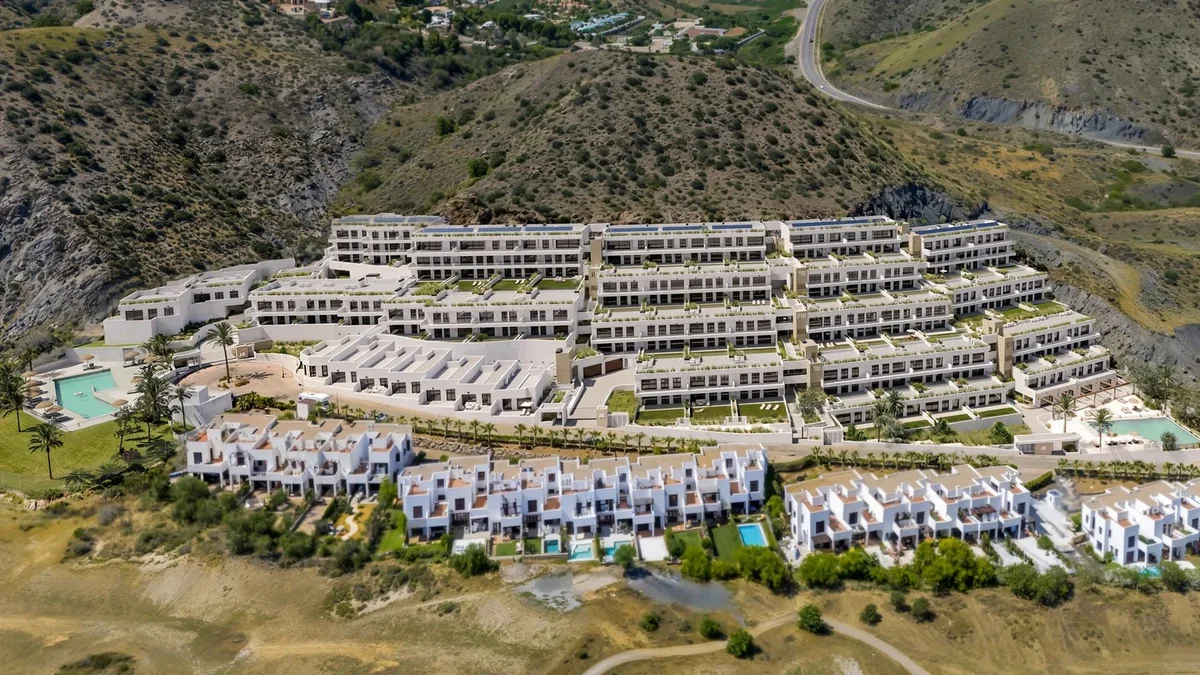
Quick answer: Grupo Insur (ISUR) is a Seville-founded developer listed on the Madrid Stock Exchange since 1984, with active Costa del Sol and Sevilla promotions including Insur Scala, Obra Nueva Mijas Balance, Insur Bermes II, and Insur Creta III. Spain recorded 714,237 residential transactions in 2025 (+11.5% year on year); Málaga province foreign buyer share reached 32.80% (Registradores). Property no longer grants Golden Visa residency after 3 April 2025. Every off-plan stage payment still requires verified aval bancario.
This page is the portfolio hub for Grupo Insur on Invest Spain Property. Read the full Grupo Insur developer review for corporate history, then drill into individual project reviews before you reserve.
Buyer hub: Start with our Spain property investment guide, can foreigners buy property in Spain, and Golden Visa ended: what to do now before you reserve any unit.
What is Grupo Insur and why does ISUR listing matter for buyers?
Grupo Insur is one of Spain’s longest-established residential groups, founded in Seville in 1945 and listed on the Madrid Stock Exchange under ticker ISUR since 1984. Listed status imposes audited reporting and investor disclosures that private promoters rarely match, which matters when you are sending six-figure stage payments on off-plan contracts.
The group operates as a vertically integrated platform: residential promotion, rental patrimonio, and construction through IDS Construcción. That structure reduces reliance on unrelated general contractors and gives corporate management direct visibility over site scheduling, procurement, and quality control on active coastal schemes. It does not eliminate municipal delay risk or guarantee on-time licencia de primera ocupación, but it lowers the finger-pointing common when a promoter and contractor dispute stalled works.
National market depth supports resale planning. INE recorded 714,237 residential transactions in Spain during 2025, up 11.5% year on year. Coastal provinces where Grupo Insur concentrates product show even heavier international participation: Alicante province foreign buyer share reached 43.29% and Málaga province 32.80%. Buyers choosing Insur Scala or Mijas Balance therefore sit inside corridors with proven exit liquidity, not thin speculative municipalities.
| Corporate fact | Detail | Buyer relevance |
|---|---|---|
| Founded | 1945, Seville | Multi-cycle operating history |
| Listing | Madrid Stock Exchange since 1984 (ISUR) | CNMV reporting and transparency |
| Integration | IDS Construcción + rental patrimonio | Build execution control |
| Costa del Sol | Marbella land since 1997 | Long coastal pipeline knowledge |
| National volume 2025 | 714,237 deals (+11.5% YoY) | Macro resale support |
| Málaga foreign share | 32.80% | International exit pool |
Comparing Insur Scala, Mijas Balance, or Sevilla schemes? Our Spain advisors can match budget, payment stages, and lawyer checklists before you reserve.
Request Grupo Insur shortlistInsider tip: Grupo Insur’s listing on the Spanish exchange as ISUR is the practical advantage for a foreign buyer. Filed accounts, published results and a regulated disclosure obligation give you counterparty information that a private promoter simply does not have to provide.
Which Grupo Insur projects should international buyers review first?
Invest Spain Property publishes four priority Grupo Insur reviews linked from this hub: Insur Scala in Estepona, Obra Nueva Mijas Balance in Mijas, Insur Bermes II in Los Bermejales Sevilla, and Insur Creta III in Entrenucleos Sevilla. Each suits a different buyer profile from coastal lifestyle second homes to Andalusian metro long-let stock.
Costa del Sol promotions target international lifestyle and rental demand. Insur Scala in Estepona lists from approximately €470,000 on completed stock in June 2026 marketing, appealing to buyers who want newer coastal apartments west of Marbella without ultra-prime Marbella tickets. Obra Nueva Mijas Balance in La Cala de Mijas lists from approximately €395,000 off-plan, sitting in the high-demand corridor between Malaga Airport and Fuengirola with strong holiday and long-let tenant pools.
Inland Andalusian schemes diversify away from pure tourism seasonality. Insur Bermes II in Los Bermejales, Sevilla, lists from approximately €495,000 off-plan, serving domestic professional tenants and university-linked demand. Insur Creta III in Entrenucleos offers chalet-format off-plan stock for buyers who prefer lower apartment density while staying inside Sevilla’s growth belt.
| Project | Municipality | From (June 2026) | Status | Review link |
|---|---|---|---|---|
| Insur Scala | Estepona | €470,000 | Completed | Insur Scala |
| Obra Nueva Mijas Balance | Mijas / La Cala | €395,000 | Off-plan | Mijas Balance |
| Insur Bermes II | Los Bermejales, Sevilla | €495,000 | Off-plan | Insur Bermes II |
| Insur Creta III | Entrenucleos, Sevilla | Confirm live list | Off-plan | Insur Creta III |
Pair project reviews with area context: property for sale in Estepona, property for sale in Mijas, and the Costa del Sol property investment guide. Off-plan buyers must read the bank guarantee off-plan Spain guide before any transfer.
Grupo Insur stock in our catalogue runs from roughly €240,000 to €470,000, which places it across the working middle of the Andalucian market rather than at either extreme. Andalucian tax applies at 10% IVA plus roughly 1.2% AJD on a new build, with Patrimonio rebated at 100% regionally, and acquisition costs of 10% to 13% sit on top of any of those prices in cash at completion. On a €395,000 apartment that is €39,500 to €51,350 outside the mortgage. Each stage payment before delivery should carry its own Ley 57/1968 certificate naming the buyer and the guaranteeing entity. Non-resident income tax then applies at 19% of net rental income for an owner resident in the EU or EEA and 24% of gross for everyone else.
How does Grupo Insur handle construction quality and delivery risk?
Grupo Insur coordinates engineering and site supervision through IDS Construcción under one corporate umbrella, which supports more predictable milestone reporting than promoters who outsource entire builds to unrelated contractors with separate cash-flow pressures.
Construction quality on Costa del Sol new builds is judged on energy performance, acoustic separation, terrace waterproofing, and durability of communal pools and landscaping. Listed developers face reputational pressure to deliver licencia de primera ocupación on schedule because delays affect quarterly disclosures. Integrated build capacity does not remove municipal bottlenecks, labour availability constraints, or inspection backlogs, but it reduces disputes over who owns delay responsibility.
Buyers should treat handover as a technical event. Commission a professional snagging inspection before signing the escritura at the notary, as explained in the snagging inspection Spain new build guide. Document every defect in writing and tie remediation to contractual deadlines. On completed Insur Scala stock, verify licencia de primera ocupación, community statutes, and tourist licence feasibility before you underwrite rental income.
Checklist: ask for two delivered schemes you can visit, the snagging process in writing, the Ley 38/1999 insurer named, the projected first-occupation date, and the community fee estimate for the completed development.
What off-plan protections apply to Grupo Insur purchases?
All staged off-plan payments on Spanish new builds must comply with deposit guarantee rules requiring individual bank guarantees. Grupo Insur operates within this framework as a listed promoter, yet buyers remain responsible for verifying a named aval bancario before every euro leaves their account.
The standard purchase path begins with a reservation contract, followed by a private purchase contract and staged construction payments, with the balance paid at notary completion once the licence of first occupation is issued. Each payment should match a guarantee certificate that names you as beneficiary, states the guaranteed amount, and identifies a solvent Spanish credit institution. Corporate brochures stating that deposits are protected are not substitutes for your individual certificate.
Red flag to verify before any transfer: Never accept a generic project-level guarantee letter that omits your name, payment date, or exact amount. If the promoter delays issuing the certificate after you sign the private contract, pause transfers and instruct your lawyer immediately.
For broader fraud patterns affecting foreign buyers, see Spain property scams to avoid and complete full legal due diligence using the due diligence Spain property checklist.
| Payment stage | Typical % of price | Guarantee action |
|---|---|---|
| Reservation | €6,000 to €12,000 fixed | Confirm refund terms in writing |
| Private contract | 20% to 30% | Named aval bancario required |
| Construction milestone | 10% to 20% each | Updated guarantee to new total |
| Completion | Balance + 10% IVA | Snagging + licencia check |
Red flag: accepting a listed promoter’s reputation in place of an individual guarantee certificate. Ley 57/1968 applies identically to ISUR and to a first-time developer, and the certificate for each staged payment is what you actually hold if delivery fails.
Two protections operate at different points and buyers often conflate them. Before delivery, the Ley 57/1968 regime requires each stage payment to be individually guaranteed, so a construction failure returns your money rather than leaving you as an unsecured creditor. After delivery, the Ley 38/1999 warranties run for 10 years on structural elements, 3 on habitability items such as waterproofing and installations, and 1 on finishes. The first protects capital during the build; the second protects the building afterwards. A resale purchase at a similar price carries neither, which is the substantive trade against a lower headline transfer tax of 7% rather than 10% IVA. On a €395,000 property that tax difference is roughly €12,000, set against protections a resale cannot offer at any price. set against protections a resale cannot offer at any price, and the buyer has to decide which of the two is worth more on the specific property.
What are the pros and cons of buying from Grupo Insur in 2026?
Grupo Insur offers listed-company transparency, Andalusian regional depth, and vertical construction control, balanced against premium pricing and limited layout customisation typical of established promoters with institutional governance.
Advantages
- Listed-company reporting: ISUR listing since 1984 imposes audited disclosures private promoters rarely match.
- Vertical integration: IDS Construcción supports coordinated scheduling and quality oversight.
- Regional expertise: Decades in Andalusia and Marbella-area land since 1997 reduce location-selection risk.
- Coastal pipeline: Insur Scala and Mijas Balance sit in high-demand corridors with strong resale liquidity.
- Legal framework alignment: Listed groups typically adhere to guarantee procedures, subject to lawyer verification.
Limitations
- Premium pricing: Long track record often commands higher entry than small local builders.
- Limited layout changes: Structural modifications are rarely permitted once engineering is fixed.
- Municipal delay exposure: Large coastal projects can still slip if town halls delay licences.
- Residency misconception: Property does not grant Golden Visa after 3 April 2025; plan visa routes separately.
Methodology: this balance weights counterparty transparency heavily, because that is what a listed promoter offers a foreign buyer who cannot visit sites easily. A buyer able to inspect and verify locally would weight specification and location higher and the listing status lower.
Which buyer profiles fit Grupo Insur promotions best?
Grupo Insur suits buyers who prioritise corporate longevity and Andalusian operating history over the lowest headline price, especially on off-plan purchases where deposit security and delivery credibility matter more than bespoke villa design.
Scenario A: Risk-aware off-plan buyer
You want a listed developer with published accounts and a traceable construction arm. Focus on Mijas Balance or Sevilla schemes, instruct a lawyer before reservation, and refuse to pay construction milestones without verified guarantees.
Scenario B: Lifestyle second-home buyer
You plan annual family use with optional long-term letting. Mijas offers airport access and school proximity; Estepona suits a quieter rhythm. Model community fees using the cost of buying property Spain guide.
Scenario C: Long-hold capital preserver
You accept moderate rental yield in exchange for brand resilience and location quality. Compare Grupo Insur entry pricing against resale stock in the same municipality before assuming new-build premium is always justified.
| Buyer profile | Best-fit project | Primary risk | Recommended action |
|---|---|---|---|
| Risk-aware off-plan | Mijas Balance, Bermes II | Missing aval bancario | Lawyer review before every payment |
| Lifestyle second home | Insur Scala, Mijas Balance | Community rental restrictions | Read draft statutes before reservation |
| Yield-focused investor | Resale compare first | Higher entry vs resale | Model net yield with real fee data |
Buyer scenario: Insur’s Seville concentration around Entrenúcleos and Tomares is where the site’s best-converting stock sits, with Elyonia from around €240,000. That is a different buyer from the Costa del Sol tier, and the delivery record matters more than the brand in both.
Buyer scenario: an income-focused buyer at the Seville entry level and a lifestyle buyer on the Costa del Sol read the same Insur brochure very differently. The first is underwriting the municipality and the tenant pool; the second is underwriting the location and the resale depth.
Closing verification checklist for Grupo Insur buyers
Before signing a reservation on Insur Scala, Mijas Balance, Bermes II, Creta III, or any other Grupo Insur promotion:
- Confirm the promoting legal entity matches contract and guarantee documents.
- Request proof of licencia de obras or verifiable municipal filing status on off-plan stock.
- Obtain a named aval bancario for each stage payment under Ley 20/2015.
- Book a snagging inspection slot before notary completion on delivered stock.
- Verify community statutes if you plan holiday rentals (VFT in Andalucia).
- Budget for 10% IVA on new builds plus notary, registry, and legal fees (~11% to 13% total in Andalucia).
- Confirm residency plans separately from property purchase after Golden Visa abolition on 3 April 2025.
Invest Spain Property field notes
We track Grupo Insur Spain Developer Portfolio Investor by phase rather than by brand. Specification, community charges and delivery performance shift between phases of one masterplan, so a delivered block you can walk through tells you more than the current renders.
| Check | What we see in 2026 files | Your action |
|---|---|---|
| Municipality rules | STR and rent caps differ by town | Confirm licence path on exact address |
| Net yield model | Gross minus 2 to 3 points typical | Include IBI, community, NRIT |
| Resale depth | Foreign share vs days on market | Two comps within 500 m before offer |
Buyer scenarios
Who you are changes what Grupo Insur is worth, and three profiles cover most buyers. Hold period, whether the plan depends on letting income, and appetite for management separate them faster than budget does. Non-resident tax at 19% or 24% applies to all three.
Portfolio landlord: Compares this guide’s market to an existing Costa Blanca holding, stress-tests NRIT at 19% EU or 24% non-EU, and reads AGM minutes for STR restrictions before exchange.
Family use plus rent: Plans eight to twelve owner weeks annually, models mid-term or long-let income for remaining months only when licence or tenancy law allows, and keeps FX and insurance in the same spreadsheet as yield.
Buyer scenario: an income-focused buyer at the Seville entry level and a lifestyle buyer on the Costa del Sol read the same Insur brochure very differently. The first is underwriting the municipality and the tenant pool; the second is underwriting the location and the resale depth.
Risks and red flags
Grupo Insur problems are rarely sudden; they show up in documents before they show up in money. The signals below account for the overwhelming majority of foreign-buyer losses in Spain, and each is verifiable in days rather than weeks. Any one of them means stop and check before another euro moves, not after.
- Andalucía concentration: Insur builds heavily around Sevilla and the Costa del Sol, so its portfolio carries correlated regional risk rather than national diversification.
- Entrenúcleos build-out: schemes like Elyonia depend on district infrastructure delivering on schedule. Verify tram extension progress and occupancy in delivered phases on the ground.
- Listed-company reporting: ISUR publishes results, which helps on solvency, but does not commit the company to any individual handover date.
- Suburban rental demand: tourist licence demand concentrates in Sevilla city rather than Dos Hermanas, so treat short-let income on suburban stock as secondary at best.
Red flag summary: a guarantee certificate missing after a staged payment, a completion estimate rather than a date in the CCPV, a first-occupation licence still pending at the promised handover, and community fee estimates that arrive only after reservation.
Market context for 2026
Grupo Insur delivered roughly 2,400 homes in 2024 with heavy Alicante and Murcia weighting. Resale liquidity on Insur Scala and similar schemes depends on orientation and finish versus €250,000 to €420,000 peers in the same urbanization. Underwrite VFT feasibility and community STR votes before you treat brochure occupancy as achievable.
Spain recorded 714,237 residential transactions in 2025 (+11.5% year on year). Foreign buyers accounted for about 13.82% nationally, with Alicante at 43.29% and Málaga at 32.80% provincial foreign share in Registradores data. Use municipality-first comps, not national averages, before you bind a deposit.
Methodology: we read a listed promoter through its filed accounts and delivery record rather than its brand. ISUR’s disclosure obligation gives a foreign buyer counterparty information that a private developer never has to publish, and that is the practical advantage here.
Resale and rental underwrite
Grupo Insur buyers in Alicante and Murcia corridors should stress-test occupancy against 43.29% foreign-share liquidity without assuming instant STR permits. Model long-let at 4.5 to 5.5% gross only after subtracting IBI, community, insurance, and 19% EU NRIT on net rent. Completed Insur phases need licencia de primera ocupación, community debt certificate, and energy certificate before notary.
Compare Insur warranty periods and snagging timelines against Neinor and Aedas deliverables in the same price band before you accept launch pricing. Request the community debt certificate and energy label on every resale unit, not only on developer direct sales.
Frequently Asked Questions
Yes. Grupo Insur trades on the Madrid Stock Exchange as ISUR and has been listed since 1984. The group was founded in Seville in 1945 and publishes corporate results on its investor site, giving buyers more transparency than many private promoters.
The portfolio hub covers Insur Scala in Estepona, Obra Nueva Mijas Balance in Mijas, Insur Bermes II in Los Bermejales Sevilla, and Insur Creta III in Entrenucleos Sevilla, plus the full developer review at /developers/grupo-insur/.
No for new applications. Spain ended the real estate Golden Visa route on 3 April 2025 under Organic Law 1/2025. Property purchases remain valid for investment or lifestyle, but residency requires separate visa routes.
Spanish law requires individual bank guarantees (aval bancario) under Ley 20/2015 and Ley 57/1968 for staged off-plan payments. Listed status does not replace your obligation to verify a named guarantee before every transfer.
Andalusia dominates the international pipeline: Costa del Sol schemes in Estepona and Mijas, plus Sevilla metro promotions. Madrid metropolitan delivered stock also appears in the corporate portfolio.
Grupo Insur differs through vertical integration via IDS Construcción and rental patrimonio, Marbella land held since 1997, and eight decades of Andalusian operating history. Compare against Aedas Homes or Neinor on guarantee discipline and regional focus before you reserve.
Insider tip: underwrite Insur stock on the municipality rather than the promoter. Their Seville concentration around Entrenúcleos sits in a different rental market from their Costa del Sol schemes, and the developer’s quality record is the same in both while the yield arithmetic is not.
Get a Spain property shortlist
Tell us your budget and market (Costa Blanca, Costa del Sol, Balearic Islands). We reply within one business day with options matched to your goals.