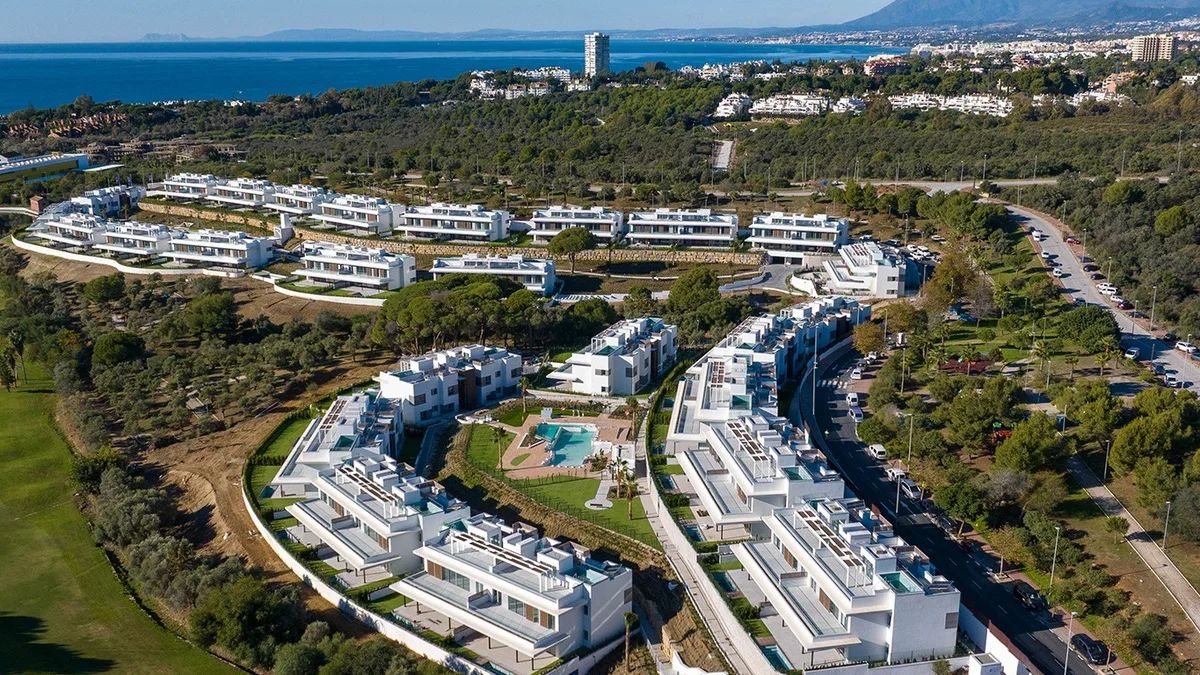
Quick answer: Neinor Homes is the largest residential developer in Spain and it is listed in Madrid, which gives a buyer something genuinely valuable: audited, regulated, published information about the company’s health. What it does not give you is protection for your money. Staged payments on an off-plan purchase are protected by an individual bank guarantee under Ley 57/1968 and by nothing else, and a listed parent’s balance sheet does not substitute for that certificate, though the two facts are frequently conflated.
What does listed status actually buy you?
A private developer tells you it is financially sound. A listed one has to prove it, on a schedule, to a regulator, in a format an auditor has signed.
That difference is the whole substance of the advantage, and it is worth more than it sounds. When you buy off-plan you are extending unsecured credit to a construction company for two or three years. Your ability to assess whether that company will still exist at handover is, for most private promoters, close to zero: you get a brochure, a sales office and whatever the internet remembers.
With a listed developer you can read the debt position and its maturity profile, the land bank and how it is funded, delivery volumes over several years against what was promised, and the auditor’s opinion including any qualification. You also inherit the scrutiny of analysts and journalists whose job is to ask uncomfortable questions on results day.
| What you can verify | Listed developer | Typical private promoter |
|---|---|---|
| Audited annual accounts | Published, regulated | Filed late, minimal, or not public |
| Debt level and maturities | Disclosed | Usually unknown |
| Delivery record against guidance | Reported and compared | Anecdotal |
| Land bank and pipeline | Quantified | Asserted |
| Independent scrutiny | Analysts, financial press, CNMV | None |
| Consequence of misstatement | Regulatory and market | Reputational at most |
None of that is a guarantee, and the distinction is not academic. Large listed developers have failed in Spain before, within living memory of this market. Listing lowers the probability of failure and raises the quality of your warning; it does not remove the risk, and it does not pay you if the risk happens.
We check the promoting entity, the guarantee wording and the milestone calendar on any development before you reserve. Independent of the developer, one business day.
Get an independent read on any Neinor schemeHow big is Neinor Homes, and why does scale matter?
Neinor describes itself as the leading residential platform in Spain and reported record results for the first half of 2026 as the country’s largest residential developer. It brought close to 50 promotions comprising around 4,000 homes to SIMA 2026, the Madrid property exhibition held that May. As of January 2026 it managed a land bank capable of developing more than 40,000 units.
Its geography spans Madrid, western and eastern Andalusia, the Levante, the Basque Country and Catalonia.
| Measure | Position |
|---|---|
| Listing | Madrid Stock Exchange, ticker HOME |
| Standing | Largest residential developer in Spain; record H1 2026 results |
| Active pipeline shown at SIMA 2026 | ~50 promotions, ~4,000 homes |
| Land bank (January 2026) | Capacity for 40,000+ units |
| Regions | Madrid, west and east Andalusia, Levante, Basque Country, Catalonia |
| Diversification | Build-to-rent and third-party asset management |
Scale changes a developer’s risk profile in ways that matter to a single buyer.
In your favour: geographic spread means no single regional downturn threatens the company. A large land bank means the pipeline does not depend on buying land in a hot market. Diversification into build-to-rent and managing assets for third parties adds income that does not depend on selling units to individuals, which is precisely the income that disappears first in a downturn.
Against you: a buyer of one apartment in a 4,000-home programme is not a significant counterparty. Responsiveness on snagging, on a delayed milestone or on a specification dispute is a function of process rather than of relationship, and processes at scale are slower and less flexible than a small promoter’s phone call.
What is the SPV question, and why does it decide everything?
Here is the mechanism that makes “listed developer” and “protected buyer” different things.
Spanish residential developments are commonly promoted through a project-specific company, a special purpose vehicle, rather than by the listed parent directly. This is ordinary and legitimate: it ring-fences each project’s financing and liabilities. It also means the entity named as promoter on your purchase contract may not be the entity whose share price and results you have been reading.
The practical consequence is a two-line check that takes minutes and settles the question:
- Which legal entity is named as promoter on the contract header? Not the brand, the registered company name.
- Does the guarantee certificate name that same entity? If the contract names one company and the guarantee names another, the guarantee may not respond to your claim.
That mismatch is, in our experience of reviewing files, the single most common serious defect in off-plan documentation, and it is invisible unless somebody compares two documents side by side. Sales offices do not do this for you. Our developer verification guide sets out the full sequence.
Red flag: a reservation conversation that answers “who is the promoter?” with the brand name rather than a registered company name, since the counterparty is the company and the brand is marketing.
What actually protects your money?
Two separate legal instruments, covering two different periods, and a buyer needs both.
Before handover: Ley 57/1968. Every amount you pay before the deed must be covered by a guarantee naming you and the exact sum, with funds held in a special account. The requirement is for an individual certificate per payment. A collective policy the developer holds, or a blanket letter issued at contract stage covering payments not yet made, is a different instrument. If four instalments are paid and three certificates exist, the fourth payment is unsecured, and buyers discover this at the worst possible moment; our bank guarantee guide sets out the wording.
After handover: Ley 38/1999. The Ley de Ordenación de la Edificación provides one year on finishes, three years on habitability defects and ten years on structural elements, all running from the reception of works. The detail is in the Ley 38/1999 warranty guide. This is backed by compulsory insurance rather than by the developer’s continued existence, which is exactly why it survives a promoter winding up an SPV after a project completes.
| Period | Instrument | What it covers | What it does not |
|---|---|---|---|
| Contract to deed | Ley 57/1968 guarantee | Each staged payment, individually certified | Anything not named on a certificate |
| Year 1 after reception | Ley 38/1999, tier 1 | Finishes and completion defects | Wear, misuse |
| Years 1-3 | Ley 38/1999, tier 2 | Habitability: damp, insulation, installations | Cosmetic issues |
| Years 1-10 | Ley 38/1999, tier 3 | Structure: foundations, load-bearing elements | Non-structural defects |
Note what is absent from that table: the developer’s credit rating, its market capitalisation, and whether it is listed at all. Those affect the likelihood you ever need to rely on the table, yet none of them appears in it.
How should you compare Neinor against another developer?
Compare them on the four things that change your outcome, and set aside brand and whether one is listed.
- The promoting entity and its guarantee. Same check for every developer, listed or not. This is the one that matters most and it is developer-agnostic.
- Delivery record in your specific region. A national developer’s overall record is less informative than what it has actually completed near your scheme, and on time.
- What is included in the price. Parking, storage, appliances and terrace size differ enormously between promoters and are worth tens of thousands. A lower headline price with parking sold separately is often the more expensive purchase.
- Responsiveness at snagging. Ask owners in a delivered scheme by the same developer how the defect list was handled after handover. This is where large organisations most often disappoint and where it is hardest to get an honest answer in advance.
Aedas Homes is the closest comparable listed counterparty on this site, and the Aedas review covers its portfolio and standards. For the full Neinor schemes list, see the Neinor Homes portfolio guide 2026. Metrovacesa is the other large listed name, covered in the Metrovacesa developer guide. Kronos Homes, covered in our Kronos review, is a design-led private group and therefore a good illustration of the disclosure gap: excellent product, far less public financial information.
What should you do before signing anything?
- Get the registered company name of the promoter from the contract header, not the brand.
- Confirm the guarantee certificate names that same entity, and confirm with the issuing bank that it is live.
- Require an individual certificate for every staged payment, and check them off as they arrive.
- Read the most recent published results if the parent is listed, focusing on debt maturities rather than headline profit.
- Ask what proportion of your specific scheme is destined for private sale rather than for build-to-rent.
- Get the building licence reference behind the milestone calendar.
- Establish the reception-of-works date at handover and diary the three Ley 38/1999 warranty expiries.
- Instruct a lawyer with no fee relationship to the developer or any introducing agent, before the reservation rather than after.
- Visit a delivered scheme by the same developer in the same region and ask two owners how snagging was handled.
Insider tip: on results day a listed developer publishes a presentation alongside the accounts, and it usually contains a slide on deliveries versus guidance. If a company has repeatedly delivered fewer units than it guided, that is a schedule-slippage signal no sales office will volunteer, and it is a fair question to raise about your own completion date. What a delay actually entitles you to, and what it does not, is covered in our guide to developer delay risk; the reservation stage where those remedies are set is covered in the reservation contract guide.
Frequently Asked Questions
The probability of the company failing is lower and the information available to you is far better. The protection on the money itself is identical: an individual Ley 57/1968 guarantee certificate naming you and the exact sum. Get that right and the developer's size becomes a secondary question.
Spain's largest residential developer, with record first-half 2026 results, roughly 50 promotions and 4,000 homes shown at SIMA 2026, and a January 2026 land bank capable of more than 40,000 units across Madrid, Andalusia, the Levante, the Basque Country and Catalonia.
A project-specific company used to promote a single development, ring-fencing its financing. It matters because the entity named on your contract may not be the listed parent whose results you read. Confirm the contract and the guarantee certificate name the same entity.
Structural elements, under Ley 38/1999, running ten years from the reception of works, alongside three years for habitability defects and one year for finishes. It is backed by compulsory insurance rather than by the developer's survival, which is why it outlasts an SPV being wound up.
It can. Neinor has expanded into build-to-rent and third-party asset management, so in some schemes a portion of the stock may be retained for letting rather than sold. Ask what share of your development is for private sale, since it affects the community's owner mix.
You get disclosure: audited accounts and a published results calendar. At this scale a buyer of one apartment in a 4,000-home programme is not a significant counterparty, so snagging and milestone responsiveness depend on process more than relationship. Ask two owners in a delivered Neinor scheme how the defect list was handled.
Neinor Homes is listed on the Madrid Stock Exchange under the ticker HOME. It builds in Madrid, western and eastern Andalusia, the Levante, the Basque Country and Catalonia, so check which regional scheme and which promoting company your contract names.
Get a Spain property shortlist
Tell us your budget and market (Costa Blanca, Costa del Sol, Balearic Islands). We reply within one business day with options matched to your goals.